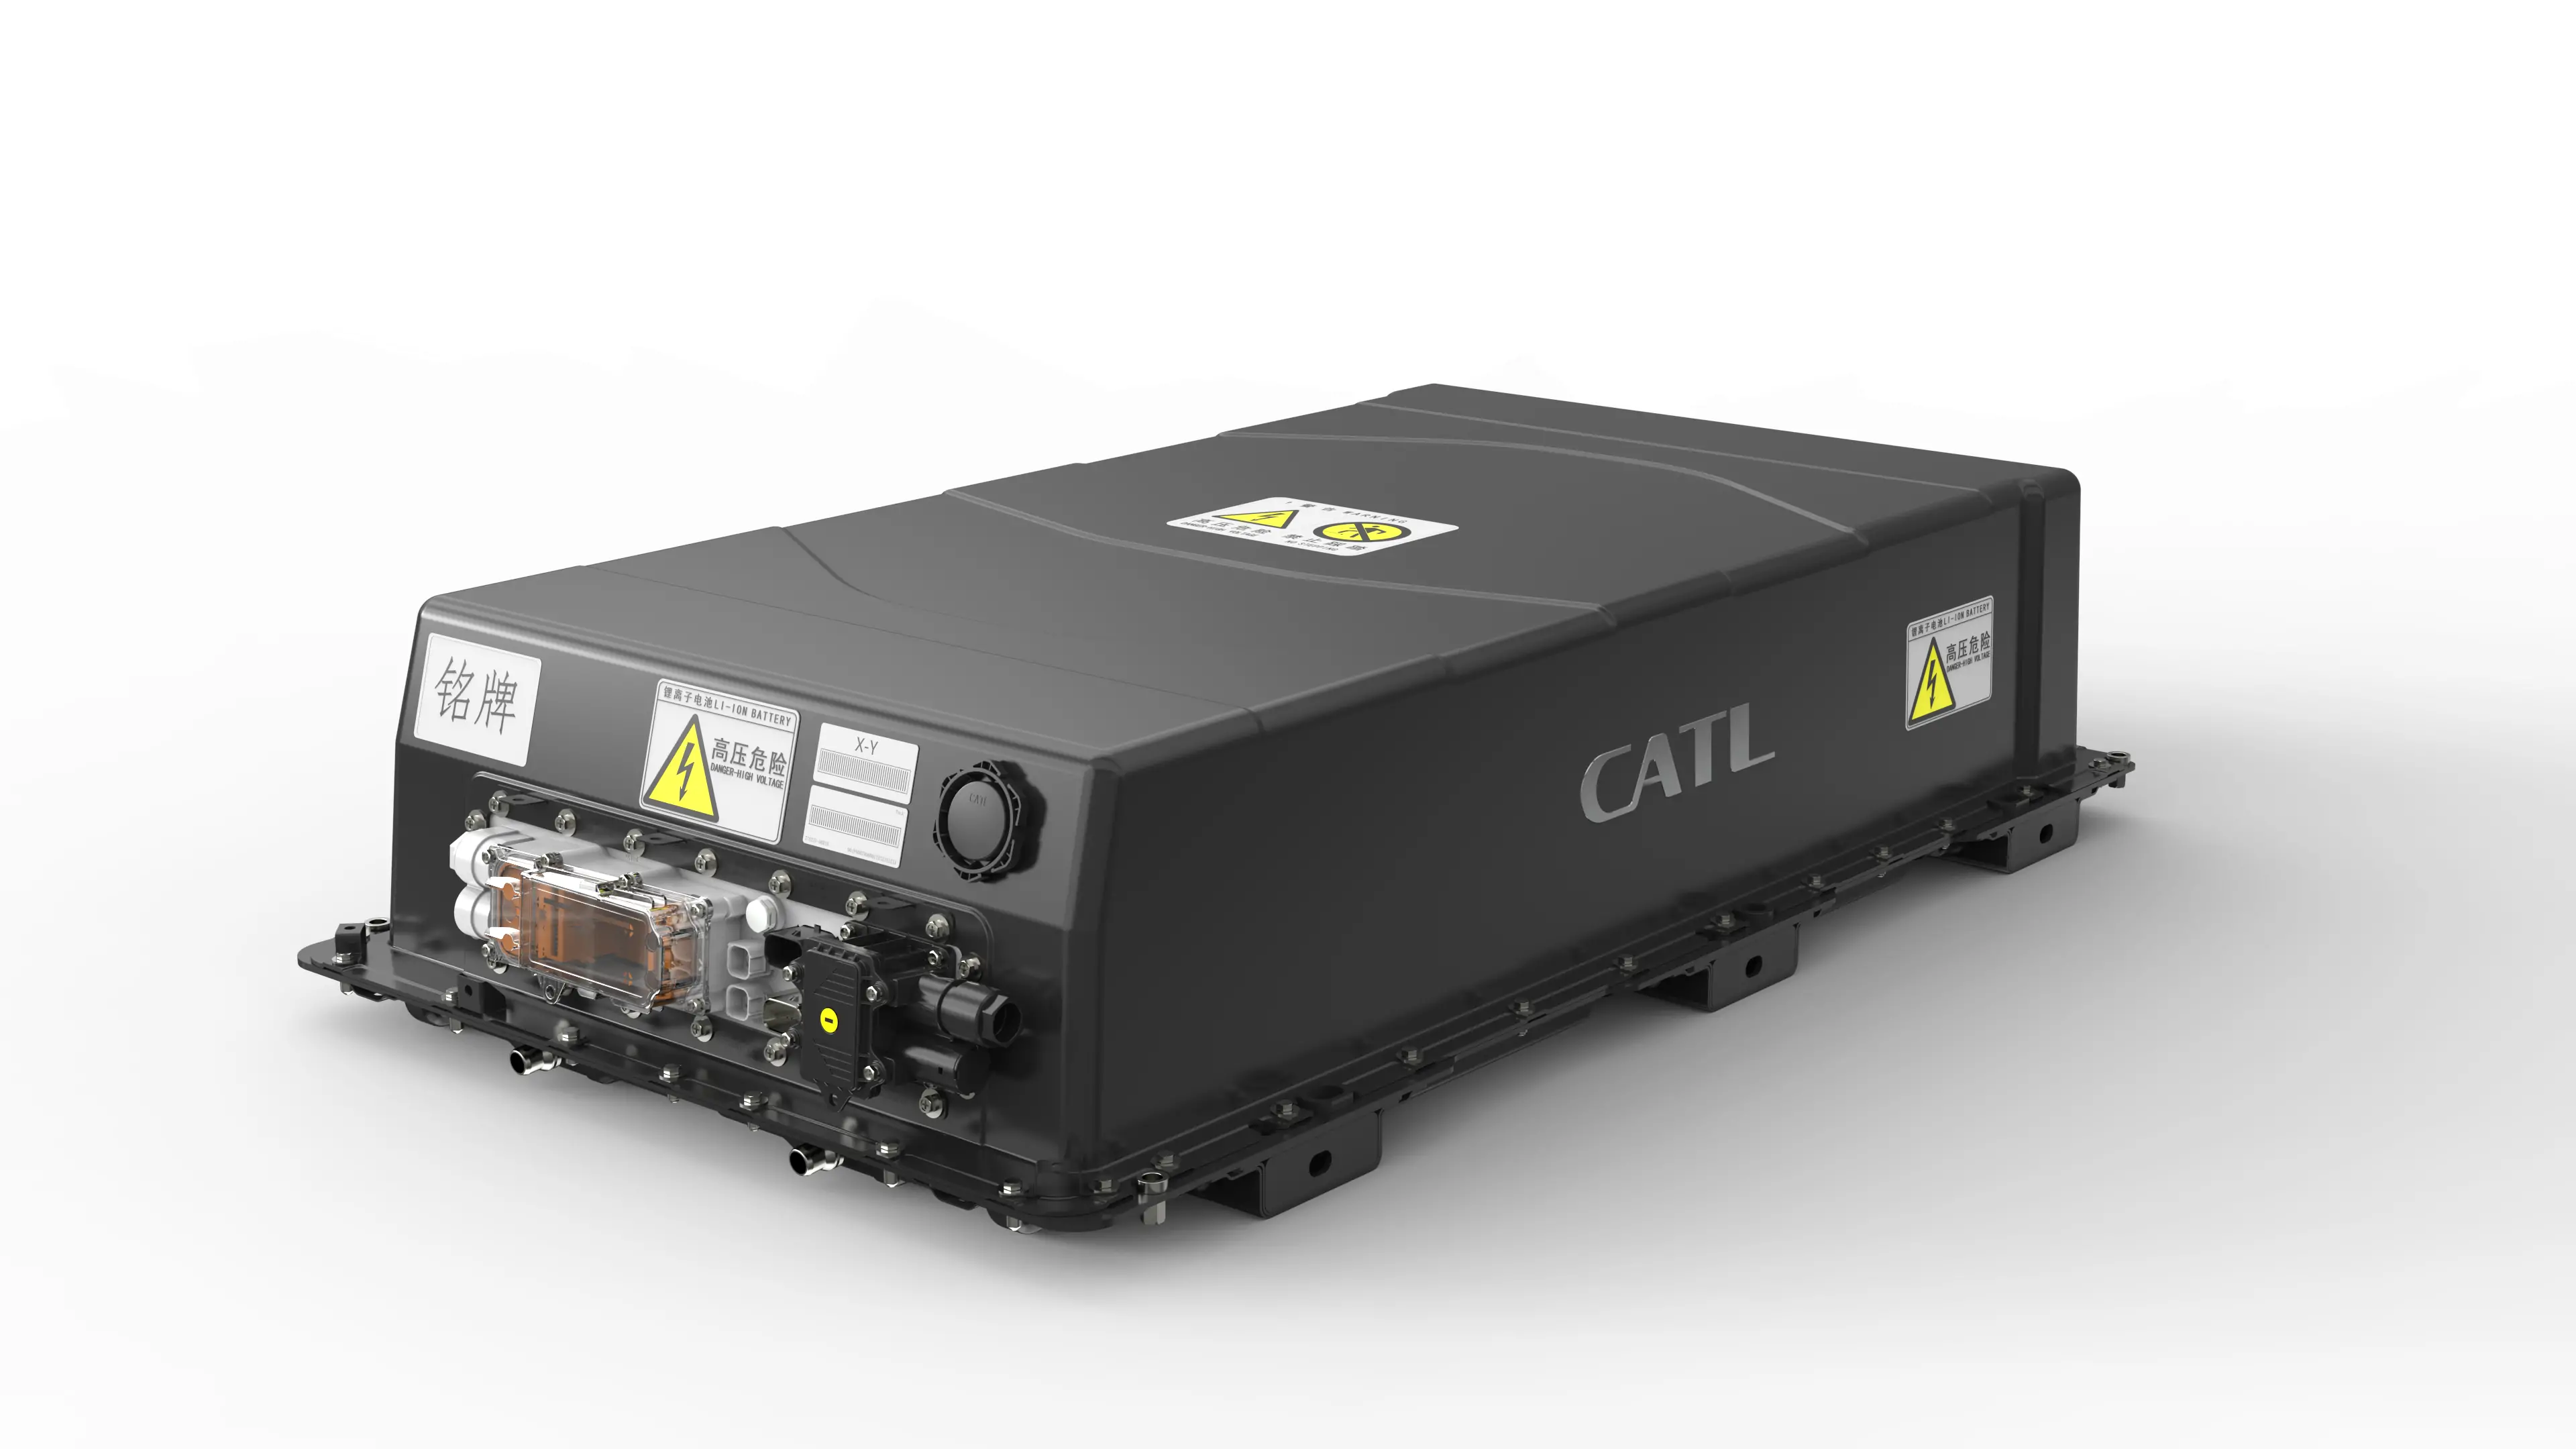
Jefferies analysts noted that robust shipment growth failed to fully offset weaker unit profitability. The company’s margins were squeezed by a shift toward energy-storage system sales, rising research and development expenditure, and inventory impairments. These challenges emerge as Chinese automakers increasingly explore in-house battery production, prompting investors to question whether the industry giant can sustain its current market dominance.
To signal confidence, CATL initiated a share buyback program in July, aiming to repurchase between $3 billion and $6 billion in stock. Bernstein analysts characterized this move as a clear statement that management views the current valuation as disconnected from the company’s long-term potential. Meanwhile, the firm is accelerating its international footprint, boosting production at its Hungarian plant and expanding battery-swapping infrastructure across Europe.
Comments (0)
No comments yet. Be the first!